General TradingB
Backtesting
Updated How we review
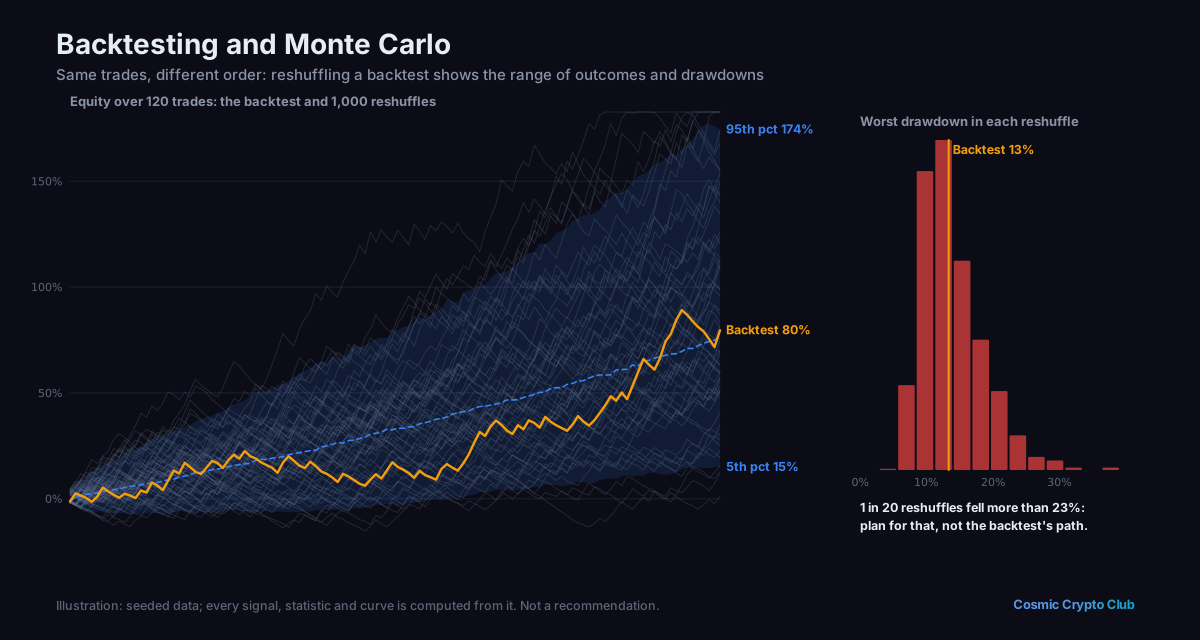
The process of applying a trading strategy's rules to historical market data to evaluate how it would have performed under past conditions. Backtesting allows traders to assess win rates, drawdowns, and risk-adjusted returns before committing real capital. Results should be interpreted cautiously, as past performance does not guarantee future outcomes and overfitting to historical data is a common pitfall.
Example
“Before going live, the trader backtested her moving-average crossover strategy on five years of EUR/USD data and found a 58% win rate with a 1.4 profit factor.”
Related Terms
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.