Risk ManagementK
Kelly Criterion
Updated How we review
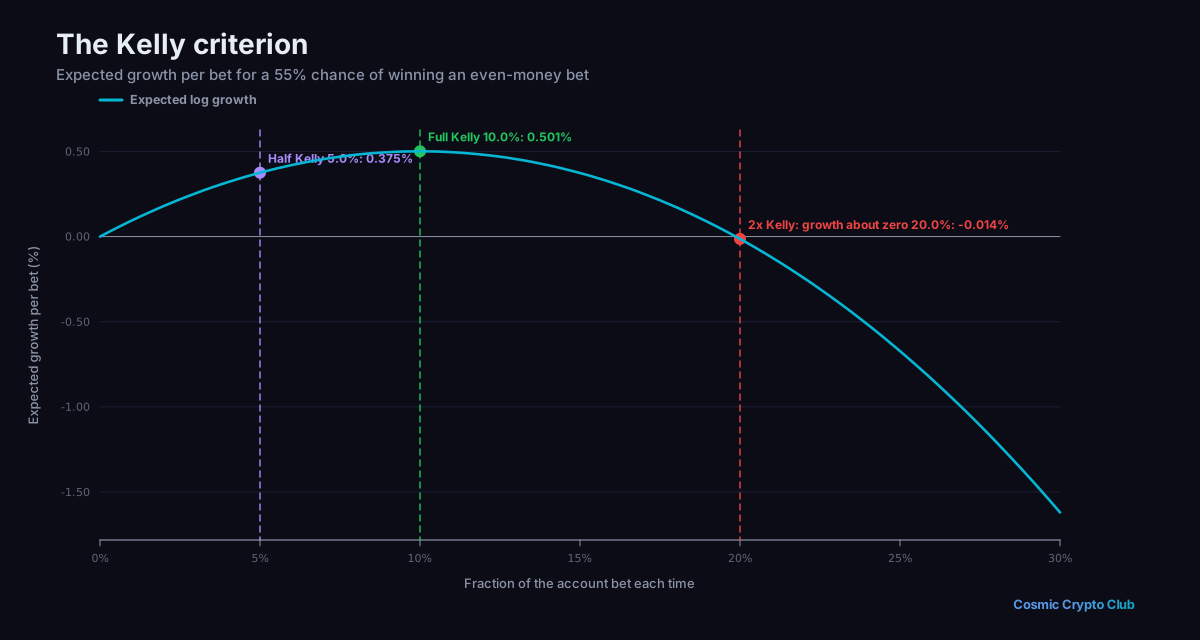
A mathematical formula used to determine the optimal size of a series of bets or investments to maximize long-term wealth growth.
Example
“For example, if a trading strategy has a 60% win rate and a 2:1 reward-to-risk ratio, the Kelly Criterion suggests risking approximately 40% of capital per trade, though most traders use a fraction of Kelly to reduce volatility.”
Full lesson
Related Terms
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.