General TradingS
Sortino Ratio
Updated How we review
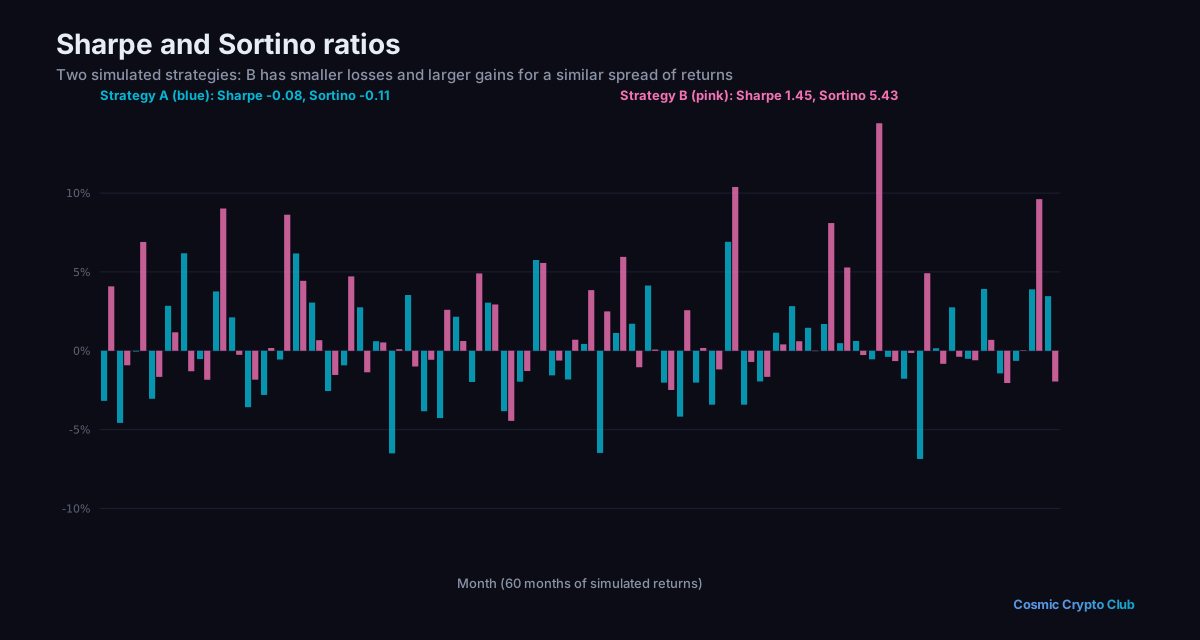
A risk-adjusted performance metric that measures the return of an investment relative to its downside risk only, ignoring upside volatility. Unlike the Sharpe ratio, it only penalizes returns falling below a target or required rate of return.
Example
“The fund's Sortino ratio of 2.1 was more impressive than its Sharpe ratio of 1.4, indicating that most of the portfolio's volatility came from positive returns rather than drawdowns.”
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.