VWAP Scalping
Updated How we review
Overview
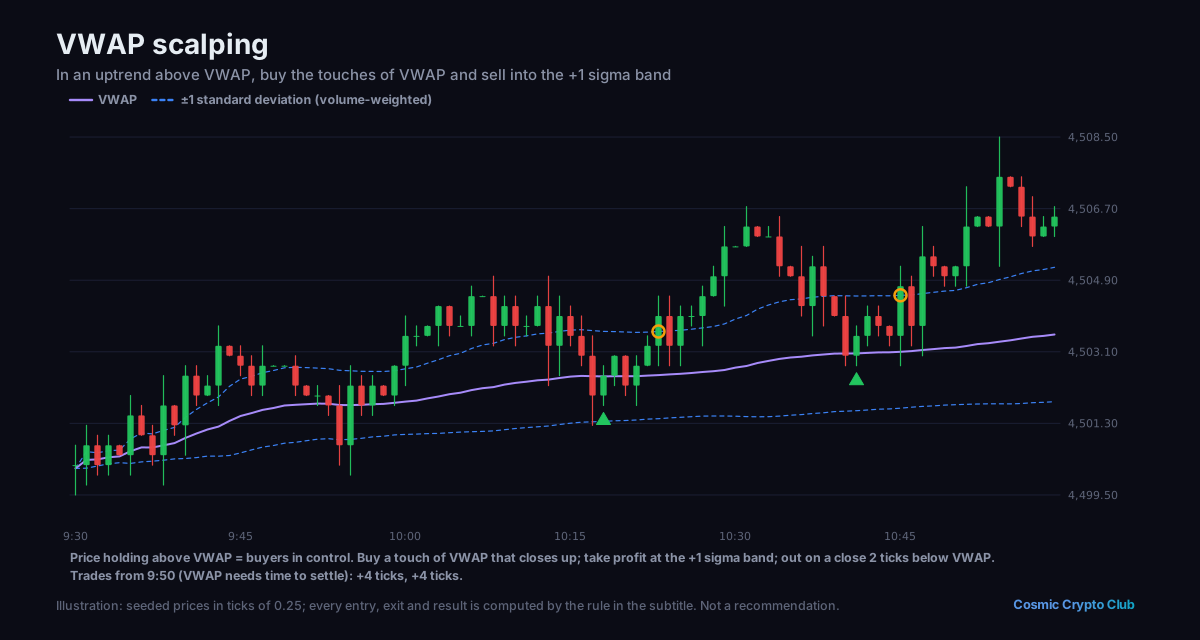
VWAP (Volume Weighted Average Price) scalping uses the VWAP line and its standard deviation bands as dynamic support/resistance for intraday scalp entries. Institutional algorithms weight their execution toward VWAP, making it a self-fulfilling level. Price below VWAP = short bias; above = long bias.
Key Concepts
VWAP resets daily (session-specific), Standard deviation bands (1σ, 2σ, 3σ) act as dynamic S/R, Mean reversion: price tends to return to VWAP, Anchored VWAP from significant events for multi-day context, VWAP slope indicates intraday trend
Entry Signals
Long entries: price pulls back to rising VWAP, holding above with volume. Short entries: price rallies to falling VWAP, rejected below with volume. Fade moves to ±2σ bands back toward VWAP. Open drive away from VWAP: trail entries in trend direction.
Exit Signals
Mean reversion target: VWAP from the bands. Trend target: opposing band. Stop: beyond VWAP (or beyond the recent swing against you). Close all positions by session end — VWAP is an intraday indicator.
Best Timeframes
1M, 3M, 5M for entries with VWAP calculated on the session
Pro Tips
VWAP is most reliable in liquid instruments (ES, NQ, SPY, major forex pairs). On low-volume instruments, VWAP becomes less meaningful because fewer institutional algorithms are using it.
Calculators for this lesson
More Topics in This Category
1-Minute Price Action Scalps
1-minute scalping uses pure price action — candle patterns, micro-structure breaks, and support/resistance — on the 1-minute chart to capture small moves (2-10 ticks in futures, 5-20 pips in forex). This is the fastest form of discretionary trading, requiring rapid decision-making, tight spreads, and minimal latency.
Momentum Scalping
Momentum scalping captures the initial burst of a move — breakouts, gap fills, news reactions, and session opens. Rather than fading moves or capturing spreads, momentum scalpers jump on explosive moves early and ride them for 5-30 ticks before the momentum fades. Speed of entry and aggressive stop management are critical.
Session Transition Scalps
Session transition scalping exploits the volatility and liquidity shifts that occur when one major trading session hands off to the next. The overlaps between the Asian-to-London and London-to-New York sessions create predictable patterns of expansion, reversal, and liquidity grabs as new participants enter and reprice the market based on their regional order flow and sentiment.
Tape Reading Scalps
Tape reading analyzes the real-time stream of executed trades (Time & Sales) and the order book (Level II / DOM) to identify institutional activity. Tape readers watch for large orders, icebergs, spoofing, and absorption patterns to scalp entries ahead of imminent price moves. This is the most granular form of order flow trading.
Explore Related
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.