Yield Curve — Inversion, Steepening & Flattening
Updated How we review
Overview
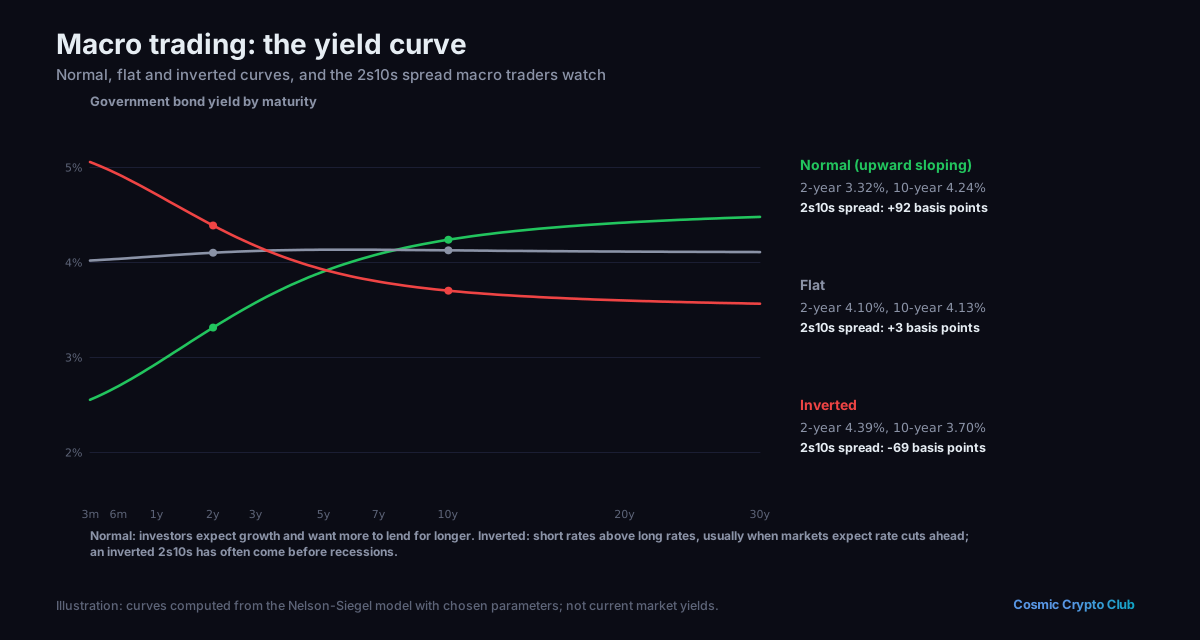
The yield curve plots interest rates across different bond maturities and is one of the most reliable recession predictors in financial markets. An inverted curve — where short-term rates exceed long-term rates — has preceded every US recession in the last fifty years, making it an essential indicator for macro traders and long-term investors alike. Understanding the differences between inversion, steepening, and flattening helps you anticipate shifts in monetary policy and equity market direction. Track the 2s10s spread and other key spreads on our yield curve page to stay ahead of the economic cycle.
Key Takeaways
- Normal curve: long-term rates > short-term rates (upward slope).
- Inverted curve: short-term rates > long-term rates — historically precedes recessions.
- The 2s10s (2-year minus 10-year yield) is the most watched spread.
- Yield curve un-inversion (steepening) often signals a recession is imminent, not that danger has passed.
Practical Tips
- Track the 2s10s spread on FRED or TradingView — it updates daily.
- An inverted curve can persist for 6-18 months before the recession hits.
- Banks suffer during inversions (compressed net interest margin) — underweight financials.
More Monetary Policy Guides
Interest Rate Cycles & Market Impact
Interest rate cycles — the multi-year pattern of rate hikes and cuts — are the single biggest driver of asset-class performance across stocks, bonds, and forex. Identifying where we stand in the current cycle helps investors decide whether to favour growth equities, defensive positions, or cash and short-duration bonds. Rate-hiking cycles compress equity valuations and strengthen the domestic currency, while cutting cycles expand multiples and support risk-on assets. Mastering these dynamics through our fundamental analysis academy will give you a significant edge in portfolio allocation and timing.
Quantitative Easing (QE) vs Quantitative Tightening (QT)
Quantitative Easing (QE) expands the money supply by purchasing bonds, while Quantitative Tightening (QT) contracts it by letting bonds roll off the central bank's balance sheet. These are the most powerful tools central banks have beyond interest rates, and their effects ripple across equities, currencies, and crypto for months after implementation. QE generally inflates asset prices by flooding the financial system with liquidity, whereas QT gradually drains it, putting downward pressure on risk assets. Understanding balance-sheet dynamics is essential for any macro trading strategy and helps explain why markets move independently of earnings.
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.