Risk of Ruin Modeling
Updated How we review
Overview
Risk of ruin calculates the probability that a trader will lose a specified percentage of their account — typically enough to end their trading career — given their win rate, average reward-to-risk ratio, and percentage risked per trade. This mathematical framework quantifies whether a trading strategy is survivable over the long run and helps traders set appropriate risk limits to ensure longevity.
Key Concepts
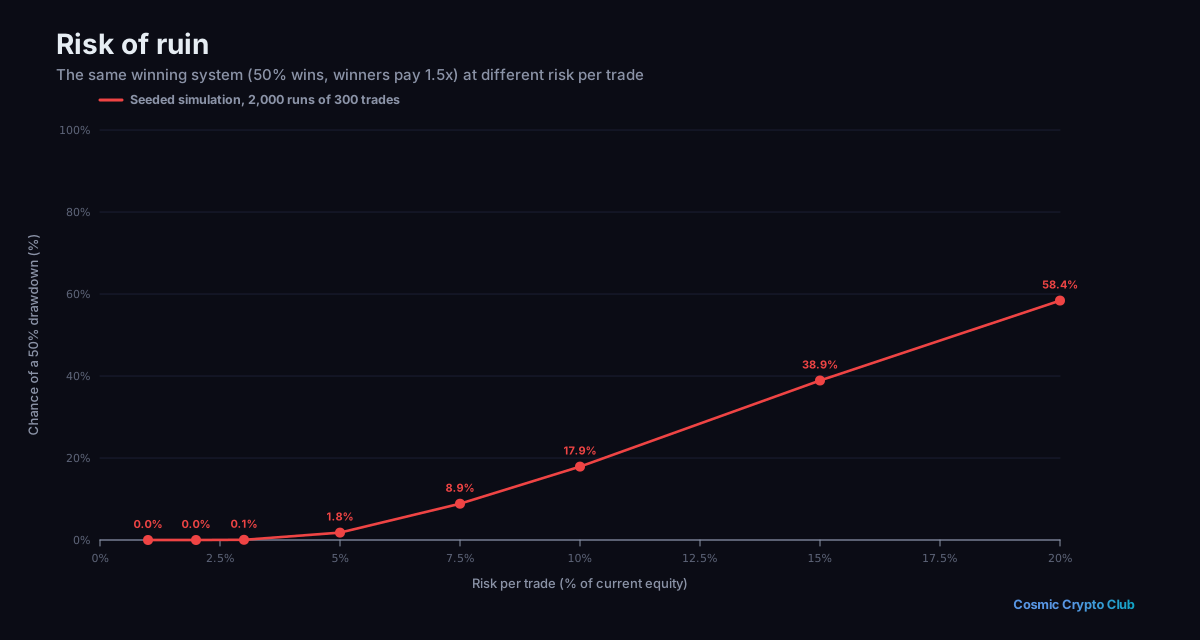
Risk of ruin is a function of win rate, reward-to-risk ratio, and percentage risked per trade. Even a profitable edge can lead to ruin if position sizes are too large. A trader risking one percent per trade with a fifty-five percent win rate has near-zero risk of ruin. The same trader risking ten percent per trade faces a substantial probability of total account destruction. Kelly Criterion calculates the optimal fraction of capital to risk for maximum geometric growth. Half-Kelly or quarter-Kelly is often preferred because full Kelly produces large drawdowns.
Entry Signals
Before trading any strategy live, calculate risk of ruin using at least one hundred simulated or backtested trades. Ensure risk of ruin is below one percent before allocating real capital. Adjust risk per trade until the risk of ruin reaches an acceptable level. Use Monte Carlo simulation to stress-test the strategy across thousands of random trade sequences.
Exit Signals
Reduce position size if drawdown exceeds the expected maximum from your simulation. Halt trading entirely if drawdown reaches a pre-defined circuit breaker level. Re-evaluate the strategy if actual performance deviates significantly from simulated expectations. Scale back to the minimum position size during extended losing streaks.
Best Timeframes
Strategy-level analysis — applied before trading and reviewed monthly
Pro Tips
Most traders never calculate their risk of ruin and are shocked to learn how close they are to account destruction. Even small changes in risk per trade produce dramatic differences in long-term survival probability. Running a Monte Carlo simulation with your actual trade data is one of the most valuable exercises a trader can perform.
Calculators for this lesson
More Topics in This Category
Maximum Drawdown Limits
A maximum drawdown limit is a predefined loss threshold that triggers mandatory action — reducing size, stopping trading, or reviewing strategy. Common limits: daily max loss (e.g., 3%), weekly max loss (e.g., 5%), monthly max loss (e.g., 10%), and total max drawdown (e.g., 20%). Professional trading firms and prop firms enforce strict drawdown rules.
Risk-Reward Ratios
The risk-reward ratio (R:R or RRR) compares the potential loss (distance to stop loss) to the potential gain (distance to target) for each trade. A 1:2 R:R means you risk $1 to potentially make $2. By maintaining favourable risk-reward ratios, a trader can be profitable even with a win rate below 50%.
Portfolio Diversification
Portfolio diversification reduces risk by spreading capital across multiple uncorrelated or negatively correlated assets, strategies, and timeframes. True diversification requires correlation analysis — holding 10 tech stocks is not diversified. The goal is to generate returns from multiple independent sources rather than relying on a single trade or strategy.
Volatility-Based Position Sizing
Volatility-based position sizing adjusts trade size according to an asset's current volatility, ensuring that each position carries a consistent dollar risk regardless of how volatile the instrument is. By dividing fixed risk by the asset's average true range or standard deviation, traders normalise risk across different assets and market conditions, preventing outsized losses during volatile periods.
Explore Related
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.