Kelly Criterion
Overview
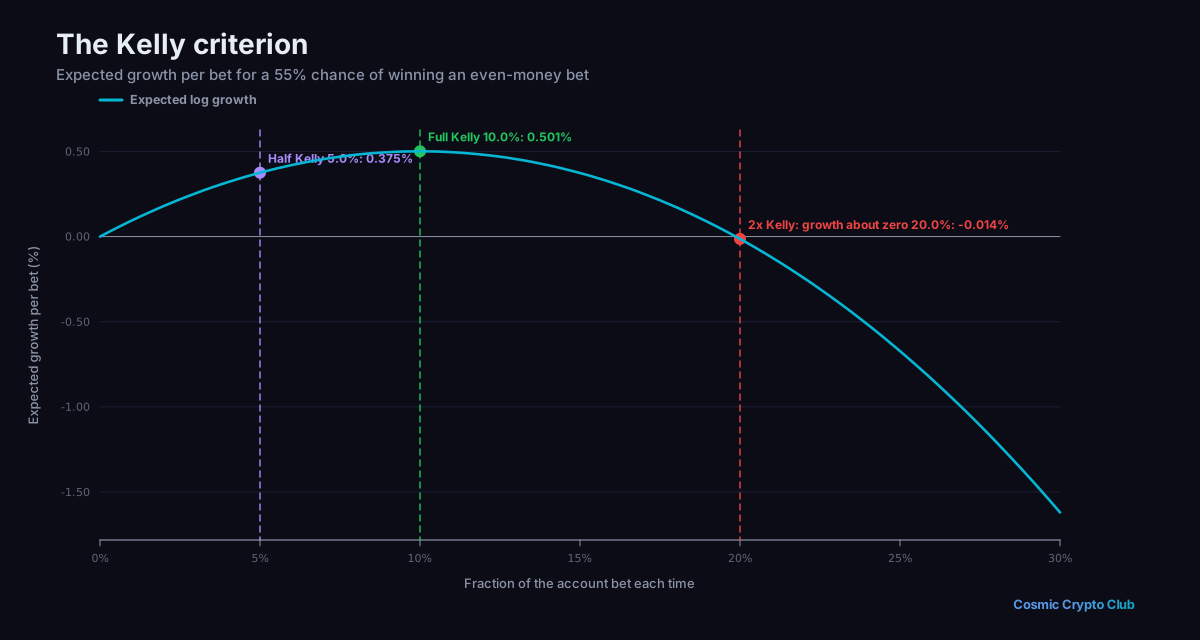
The Kelly Criterion is a mathematical formula for determining the optimal bet size to maximise long-term growth rate. Kelly = (bp - q) / b, where b = odds received, p = probability of winning, q = probability of losing. While theoretically optimal, full Kelly is too aggressive for most traders — half-Kelly or quarter-Kelly is more practical.
Key Concepts
Kelly % = (Win% × Average Win/Average Loss - Loss%) / (Average Win/Average Loss). Full Kelly maximises geometric growth but with extreme variance. Half-Kelly: 75% of full Kelly's growth with significantly less variance. Requires accurate estimation of win rate and payoff ratio. Overestimating edge leads to ruin with Kelly.
Entry Signals
Calculate the Kelly percentage from your historical trade data. Apply half-Kelly for practical use. Example: 55% win rate, 1:1.5 payoff ratio → Kelly = (0.55 × 1.5 - 0.45) / 1.5 = 25%. Half-Kelly = 12.5%.
Exit Signals
If your measured edge (win rate, payoff) decreases, Kelly size decreases. During drawdowns, reduce to quarter-Kelly. Review and recalculate monthly with updated statistics.
Best Timeframes
Applies to overall position sizing strategy, not individual trade management
Pro Tips
Kelly Criterion is theoretically elegant but dangerous with imperfect data. Most traders don't have enough trade history for reliable win rate and payoff ratio estimates. Use Kelly as a ceiling, not a floor.
More Topics in This Category
Hedging Fundamentals
Hedging is the practice of taking offsetting positions to reduce exposure to adverse price movements in your primary holdings. Rather than closing a profitable position or accepting full downside risk, hedging allows traders to protect capital during uncertain periods while maintaining their core exposure. Effective hedging balances protection cost against the risk being mitigated.
Maximum Drawdown Limits
A maximum drawdown limit is a predefined loss threshold that triggers mandatory action — reducing size, stopping trading, or reviewing strategy. Common limits: daily max loss (e.g., 3%), weekly max loss (e.g., 5%), monthly max loss (e.g., 10%), and total max drawdown (e.g., 20%). Professional trading firms and prop firms enforce strict drawdown rules.
Fixed-Fractional Position Sizing
Fixed-fractional position sizing risks a fixed percentage of your account on every trade (commonly 1-2%). This ensures that a string of losses reduces position sizes proportionally, protecting capital during drawdowns. It's the most widely recommended position sizing method for discretionary traders because it's simple, sustainable, and mathematically sound.
Sharpe & Sortino Ratios
The Sharpe ratio measures risk-adjusted return by dividing excess return (above the risk-free rate) by the standard deviation of returns. The Sortino ratio improves on Sharpe by penalising only downside deviation, recognising that upside volatility is desirable. Both ratios help traders compare strategies on a level playing field and identify which approaches deliver the best returns for their level of risk.
Explore Related
Talk it through with other traders
Ask questions and discuss what you've learned in the Cosmic Crypto Club Discord. It's free, and so are the courses in the Hub with a Discord sign-in.