VWAP Calculator
Calculate the Volume Weighted Average Price from high, low, close and volume data.
Typical Price
1.10067
Cumulative Volume
50,000
VWAP
1.10013
How the VWAP calculator works
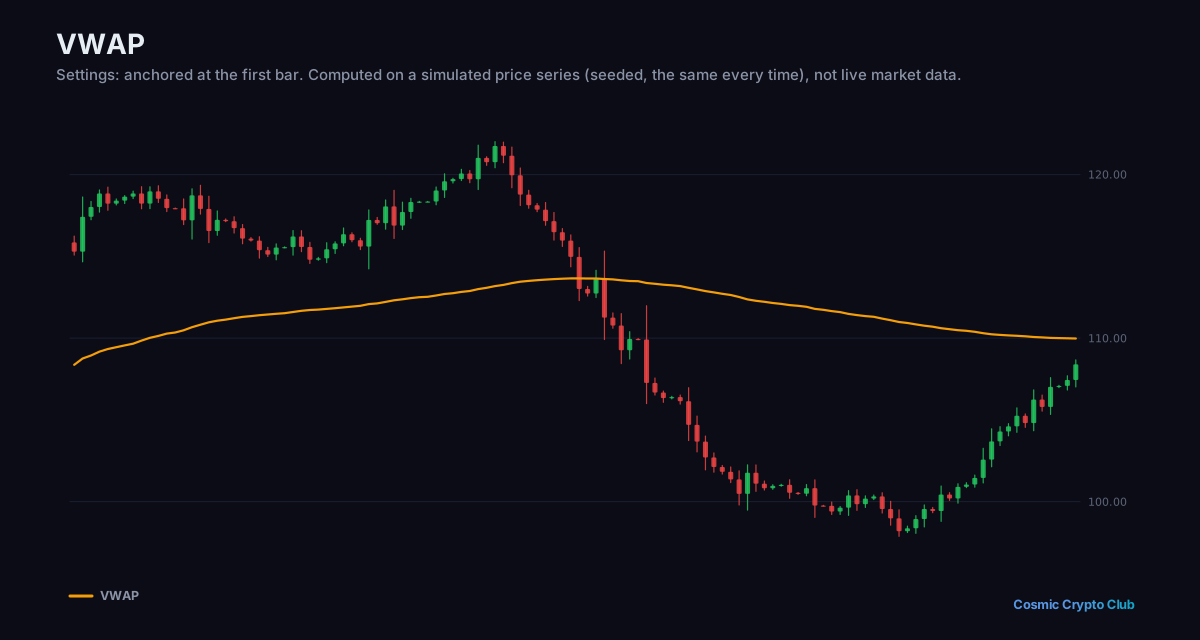
The calculator updates the Volume Weighted Average Price with one new bar. It takes the bar's typical price, the average of its high, low and close, and weights it by the bar's volume. That is added to the total so far, the previous VWAP times the volume traded before the bar, and divided by the new cumulative volume.
Typical price = (High + Low + Close) / 3
Cumulative volume = Previous cumulative volume + Interval volume
VWAP = (Previous VWAP x Previous cumulative volume + Typical price x Interval volume) / Cumulative volume
Worked example
So far today 8,000 shares have traded at a VWAP of $100. The next bar has a high of $103, a low of $101 and a close of $102 on 2,000 shares.
- Typical price: (103 + 101 + 102) / 3 = 102
- Price x volume so far: 100 x 8,000 = 800,000
- Add the new bar: 800,000 + 102 x 2,000 = 1,004,000
- Cumulative volume: 8,000 + 2,000 = 10,000
- VWAP: 1,004,000 / 10,000 = 100.40
The calculator shows a typical price of 102, a cumulative volume of 10,000 and a VWAP of 100.4.
Frequently asked questions
What is VWAP?
It is the average price traded during a session, weighted by volume: the running total of typical price times volume, divided by the running total of volume.
Does VWAP carry over to the next day?
No. It is calculated from the first trade of the day and starts again at the next open.
What do I enter for the first bar of a session?
Set the previous cumulative volume to 0. The VWAP is then that bar's typical price.
More Technical Calculators calculators
More tools in the Hub
Premium opens the Hub's Analytics section: market data, research, radars, screeners, macro, calculators and backtesting. The website and the Discord stay free.